Loan origination systems weren’t really built for constant change. Most of the time, if Risk or Product wanted to change something, Engineering had to do it.
So Risk teams worked around the gaps. Product teams put requests into the roadmap and waited for them to get picked up. And every new product, partner or regulatory change could turn into another engineering project.
That becomes a problem when the business needs to move quickly. A new loan product shouldn’t require a core-system build every time. Adding a partner shouldn’t mean hard-coding another set of rules. And a regulatory change shouldn’t have to sit in a backlog for weeks while someone figures out how to implement it.
Some lenders have started moving away from this model.
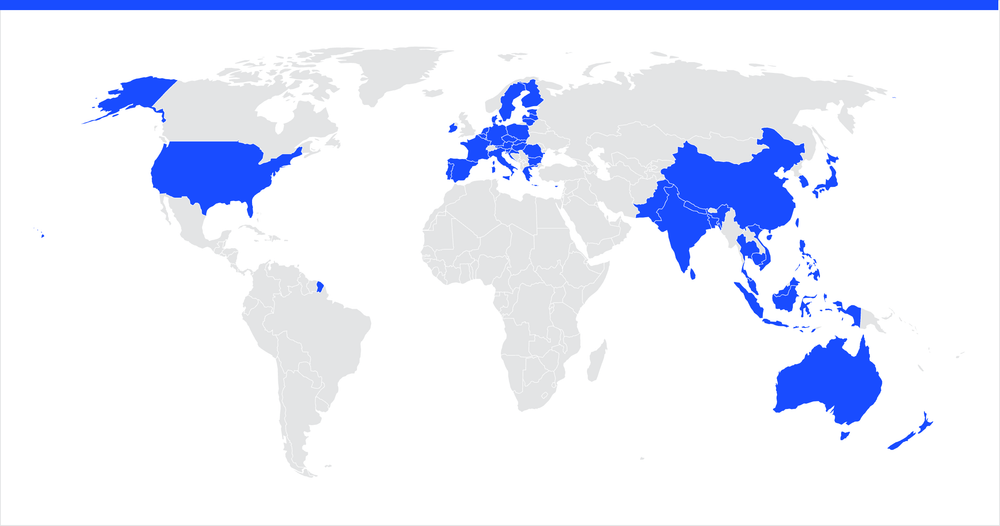
We looked at three: one in the US, one in Europe and one in India. Their approaches are quite different, but they’re solving the same underlying problem: how do you let Risk and Product change the lending process without having to go through Engineering for every little thing?
Here’s how they approached it.
US: Live Oak Bank rebuilt its SBA lending pipeline around an automated origination platform
American Banker's reporting on Live Oak Bank's SBA lending automation describes a concrete shift already under way at Live Oak Bank. The bank has been piloting an automated origination platform for its smaller-dollar SBA loans, with the aim of cutting origination times to as little as seven days. Live Oak originated $56 million through its smaller-dollar SBA program in the first quarter of 2026, and executives have projected that annual small-dollar originations could soon top $750 million.
The bank's own leadership has been pretty direct about why it is doing this. Live Oak says it is working with Casca to automate its Live Oak Express loan process and ultimately expand the technology across the bank to speed up lending workflows.
That matters because the old process was heavily manual. In its annual report, Live Oak described employees working through tax returns, budgets and financial statements to assess small-business borrowers, a process that could take weeks. The bank said AI and OCR could reduce much of that work to minutes or seconds.
The pressure to fix this isn't unique to Live Oak. Celent's 2025 Global Commercial Banking Onboarding Survey, which surveyed 409 bankers across North America, EMEA and Asia-Pacific, found that commercial onboarding still takes an average of 49 days and costs roughly $14,700 per client. It also found that 66% of banks ask customers for the same information more than once.
And lenders aren't putting all their technology investment into the borrower-facing experience. STRATMOR Group's 2025 Technology Insight Study, based on nearly 80 lenders, found that:
- 65% plan to invest in document extraction
- 52% in income extraction
- 48% in document classification
The point is fairly simple: a better-looking application doesn't fix a slow process underneath it. A lot of the work now happening in lending technology is about taking manual work out of the back office and making origination itself faster.
EU: Ibercaja spun up an entirely new lending entity rather than patch its old one
Ibercaja Banco took a different route. Instead of trying to modernise its existing lending stack piece by piece, the Spanish bank created a separate consumer finance business, Presto, and put it on a composable cloud platform.
Fintech Futures reported on Ibercaja's six-year partnership with Mambu, which was designed to move the bank's consumer finance operations onto Mambu rather than simply retrofit the existing core. Ibercaja Technology Solutions was created as part of that rollout.
The new setup was built to move faster. Ibercaja's Mambu case study says Presto was launched in eight months, starting with point-of-sale financing in vehicle dealerships in July 2025. Ibercaja is targeting 200,000 new customers within five years and plans to expand the platform into other consumer-finance use cases.
There's another reason this kind of flexibility matters in Europe right now. Consumer-credit regulation is changing, and implementation isn't necessarily identical from one market to another. The EU's Consumer Credit Directive II expands the scope of consumer-credit rules, including areas such as BNPL and smaller forms of credit, while individual countries are translating the directive into national rules.
Germany, Denmark, Sweden and Spain illustrate the differences:
- Germany has moved to bring additional forms of credit, including certain BNPL and smaller-loan products, within the regulatory framework.
- Denmark is implementing the directive with an effective date of November 2026.
- Sweden has proposed its own approach to smaller BNPL assessments.
- Spain has been developing additional consumer-credit rules around areas including pricing and licensing.
For lenders, that creates a technology problem as much as a compliance one. If the rules change by market, the lending system needs to be able to accommodate those changes without turning every update into a core-system project.
That's what makes Ibercaja's approach interesting. Presto was built separately from the legacy core, giving the bank a new environment in which to launch and change consumer lending products. The lesson isn't that every lender needs to create a new entity. It's that the lending platform can't become the thing slowing the business down.
APAC: IIFL Finance rebuilt its rules engine and turned reach into a policy problem, not an engineering one
IIFL Finance, one of India's largest NBFCs, adopted FinBox's Sentinel platform to disburse personal and business loans at scale after concluding that its existing hard-coded rules engine couldn't keep pace with the complexity of its digital lending partnerships. As Mehekka Oberoi, Director of IIFL Open Neobank, put it: the transition from a hard-coded rules engine to a centralised system of rules management was inevitable, and the real challenge was picking the right one from an increasingly crowded market.
The results, confirmed by IIFL Finance directly, were concrete:
- Turnaround time on policy deployment fell by over 95%
- Reach increased by 352%
- The number of active lending policies expanded from 64 to 177, as part of deliberate risk diversification
IIFL went from running 64 policies to running 177, meaning its risk team could differentiate credit decisions by partner, product and segment at a scale a hard-coded system simply couldn't support.
Three lenders, three different starting points, one thing worth checking on your own stack
Live Oak Bank rebuilt its SBA origination pipeline around automation instead of manual document review. Ibercaja built an entirely new lending entity rather than retrofit its legacy core. IIFL replaced a hard-coded rules engine and used the resulting flexibility to run more than twice as many credit policies as before.
Different regions are dealing with different challenges, but they’re moving in the same direction: giving business teams more control over origination, instead of leaving everything to engineering.
If you're benchmarking your own setup, three honest questions are worth asking:
- If you wanted to run more differentiated credit policies by partner or segment tomorrow, the way IIFL went from 64 to 177, would your rules engine let you, or would it need an engineering release first?
- If you wanted to launch a new lending product without touching your legacy core, the way Ibercaja built Presto, could you do that on your current platform?
- Is your next platform investment going towards something borrower-facing or toward the back-office extraction and policy work that's moving the needle for the lenders above?
This is the design brief behind FinBox LOS: a modular, API-first origination platform with 30-plus pre-built integrations across KYC, bureau, open banking, payments and loan management systems, with a central policy engine that keeps credit rules consistent across direct channels, partner journeys and embedded flows, so a new market, a new rule, or a new policy is a configuration, not a rebuild.